
Available for enterprise demonstrations and scoped implementations

Finance productive assets from application to final repayment.

Connect suppliers, financing teams, customers, payments and asset operations through one configurable platform—built for green mobility and adaptable to wider asset-finance portfolios.

Codefremics provides the technology. Your institution keeps licensing, credit policy and decision authority.

platform modules, from supplier onboarding to audit
9
lifecycle stages on one governed record
6
operating roles, from supplier to auditor
7
assistance across origination, servicing and collections, with human sign-off on credit
AI
Why a unified platform

Most asset-finance stacks stop where the asset starts.

Loan software manages the money. Device platforms manage the hardware. Asset-finance programmes need both—with suppliers, mobile-money reconciliation and investor evidence—on one governed record.

A comparison of common approaches, not of any named product. Capability status and integrations are confirmed for each engagement.
What the programme needsCodefremics Asset FinancingLoan-management softwarePAYGo and device platformsIn-house build
Supplier and asset distributionSupplier & asset marketplaceVariesCoreBuild and maintain
Origination, decisioning and servicingOrigination to servicing modulesCoreVariesBuild and maintain
Mobile-money collection and reconciliationAllocation and reconciliationVariesCoreBuild and maintain
Physical-asset lifecycle and field operationsAsset lifecycle & servicingLimitedVariesBuild and maintain
Vehicle, battery and telematics recordsGreen Mobility EditionLimitedVariesBuild and maintain
Investor, audit and sustainability evidencePortfolio and impact intelligenceVariesVariesBuild and maintain
Governed AI and automation with full audit historyAutomation with human sign-offVariesVariesBuild and maintain
Platform architecture

Nine modules. Six stages. One governed record.

Each module is configured against approved product policy, legal responsibilities, integrations and demonstrated product status.

  1. 01ConfigureSuppliers, assets, products, markets and roles.
  2. 02OriginateQuotation, onboarding, application and evidence.
  3. 03DecideRules, affordability, review, conditions and approval.
  4. 04DeliverAgreement, serial capture, acceptance and settlement.
  5. 05ServiceSchedules, payments, allocation and reconciliation.
  6. 06ManageCollections, asset lifecycle, risk and reporting.
Stages 01–02

Acquire and originate

  1. 01Supplier & asset marketplace

    Supplier onboarding and approval · Asset catalogues, eligibility and quotations · Serialised inventory, delivery and settlement

  2. 02Customer & business onboarding

    Individual and business journeys · Consent, document and exception workflows · Verified identity and data-provider integrations

  3. 03Origination & product configuration

    Deposits, terms, schedules and required evidence · Supplier-, lender-, customer- or API-led applications · Eligibility and affordability calculations
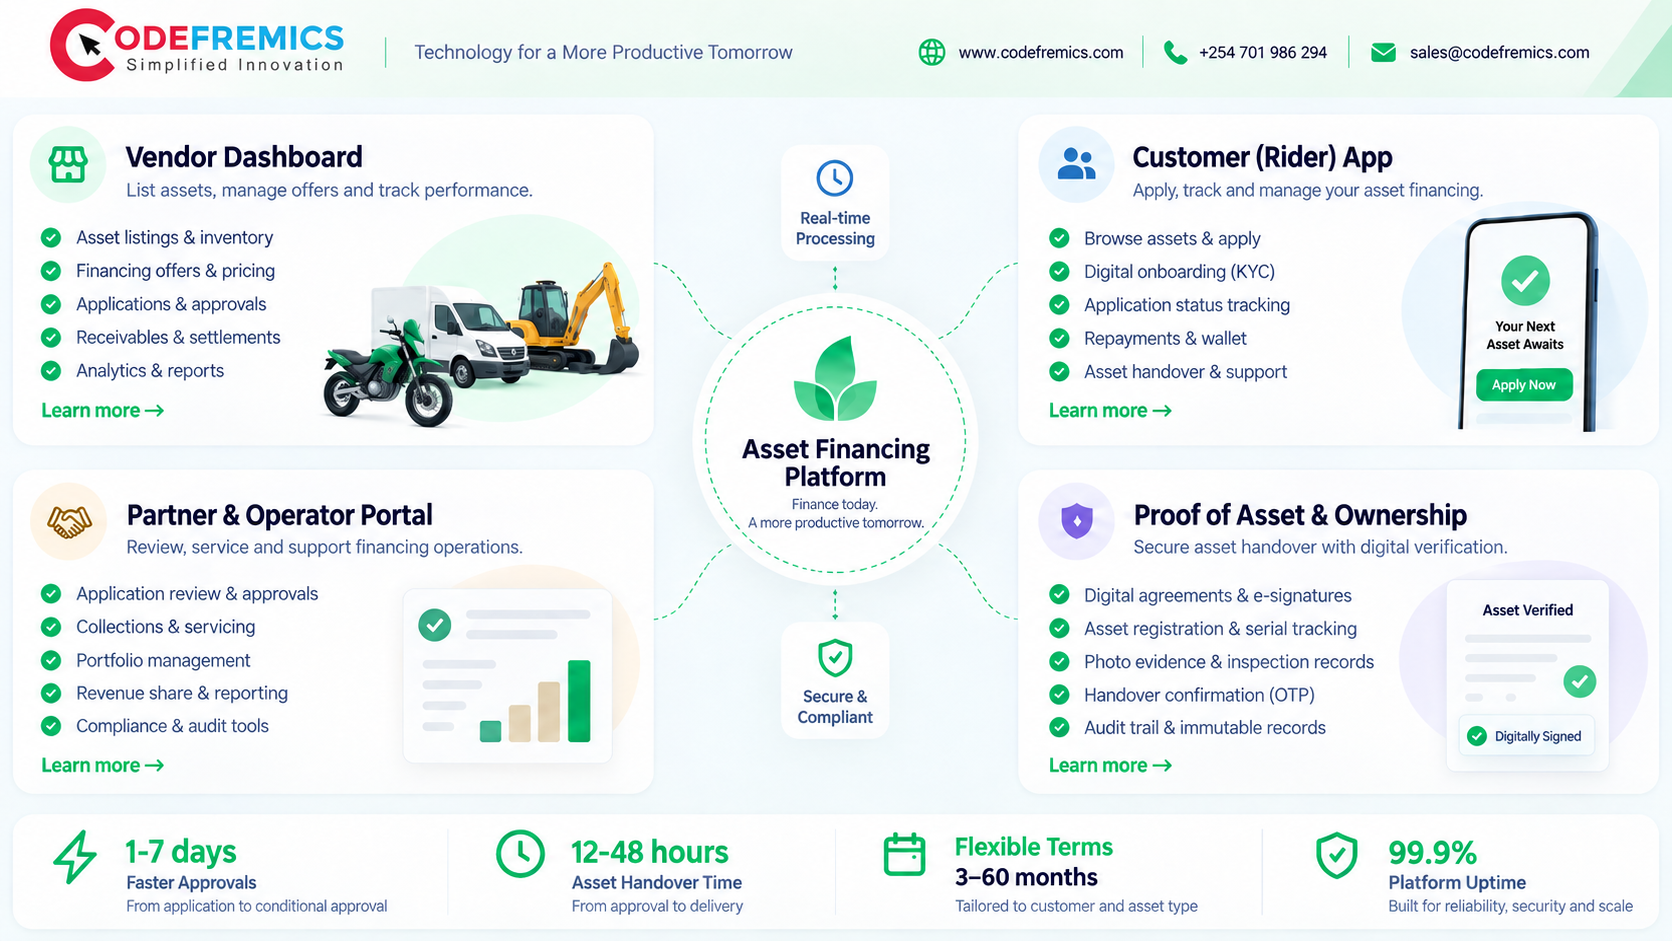
Stages 03–05

Decide, deliver and service

  1. 04Decisioning & approvals

    Human review queues and reasoned decisions · Maker-checker, limits, referrals and exceptions · Versioned rule, score and override audit history

  2. 05Agreement, delivery & settlement

    Offer, conditions and agreement workflows · Delivery evidence and customer acceptance · Approved supplier-settlement orchestration

  3. 06Repayment & account servicing

    Configurable approved schedule patterns · Payment allocation, statements and payoff · Refund, reversal, suspense and reconciliation

Stage 06

Operate and oversee

  1. 07Collections & recovery

    Arrears queues and treatment workflows · Promise-to-pay, hardship and restructuring cases · Controlled recovery, resale and closure records

  2. 08Asset lifecycle & servicing

    Ownership, custody, insurance and warranty · Maintenance, replacement and claim events · Transfer, recovery, recycling and disposal

  3. 09Portfolio, risk & audit intelligence

    Portfolio performance and concentration · Arrears, cure, recovery and reconciliation views · Permission-aware finance and audit exports

Asset Financing Platform overview
Platform configurationOne financed e-mobility customer
  • VehicleChassis, motor and registration
  • BatterySerial, capacity and warranty
  • ChargerCharging equipment record
  • Swap subscriptionBilled separately where it differs
  • Service planMaintenance and warranty events
Green Mobility Edition

Launch financing for e-bikes, batteries and clean-energy assets.

Represent vehicles, batteries, chargers, swap subscriptions and service plans separately when ownership or billing differs—then connect delivery, repayment, maintenance and end-of-life records.

  • Electric bicycle, motorcycle, fleet and productive-use asset configurations
  • Supplier, assembler, charging, swapping, maintenance and insurer relationships
  • Approved telematics, battery-management and usage integrations
  • Traceable green-asset and impact records with method and uncertainty boundaries
  • Controlled export to the Sustainability & Carbon Intelligence Platform
Discuss a green-mobility finance programme
Automation with accountable control

Automate the operation. Keep authority where it counts.

Automation handles the volume: documents, checks, calculations, allocation and signals. Authorised people own the decisions your regulators, customers and board hold you to.

Automation handles

  • Document extraction
  • Provider checks
  • Eligibility and affordability calculations
  • Payment allocation and reconciliation
  • Anomaly signals
  • Forecasting
  • Staff copilots

Authorised people decide

  • Credit approval and decline
  • Pricing and terms
  • Restructuring and recovery
  • Asset-control actions

Each decision is recorded with its reason, reviewer, rule and model version, so automation can scale without losing accountability.

Grounded suggestions

Surface source data, provider or model version, confidence, reason and correction paths.

Human approval

Require authorised review before suggestions affect product terms, decisions, customer treatment or asset controls.

Measured operation

Evaluate accuracy, drift, bias, overrides and portfolio outcomes with logged fallback and escalation.

Governance and enterprise readiness

Built to stand up to board, risk and audit scrutiny.

The questions a board asks before committing to a financing platform—and how the platform is designed to answer them.

Who makes the credit decision?

Authorised people and institutions. The platform orchestrates approved rules, scores and evidence, and records every decision, override and approval.

Can it run across markets?

Approved currencies, languages, time zones, address formats, products, schedules and reporting definitions are configured by market.

How does it connect to our estate?

Through versioned APIs, webhooks and controlled batch exchange with identity, payments, e-signature, messaging, accounting, insurance, telematics and data platforms.

How is it secured and audited?

Tenant controls, role-based access, audit events, encryption, monitoring, backups and recovery, within agreed support boundaries.

What will management and investors see?

Permission-aware portfolio, arrears, recovery, reconciliation and audit views, with metric definitions agreed for your book.

How do we start without a big-bang programme?

Begin with one edition and market, then add servicing, collections, asset lifecycle and enterprise controls on the same platform.

Codefremics provides

  • Configurable technology and implementation services
  • Workflow, integration, data and operational controls
  • Deployment, support and change services as contracted

The financing institution owns

  • Licensing, product policy and affordability approach
  • Approval or decline authority and customer disclosures
  • Collections, recovery, regulatory reporting and market compliance

Codefremics is presented here as a technology provider, not as the lender. The platform does not promise financing, guaranteed approval or a specific regulatory outcome. Review how we work in the Trust Center.

Editions

Start where the value is. Expand on one platform.

Start with a supplier or origination edition, then add servicing, green-mobility and enterprise capability. Scope, markets and commercial terms are agreed during discovery.

  1. Entry point

    Supplier Finance Portal

    For green-asset suppliers and distributors

    Supplier onboarding, asset catalogue, quotation, customer application, status, delivery, settlement and reporting.

  2. Entry point

    Finance Origination

    For banks, microfinance institutions and fintech lenders

    Products, onboarding, documents, provider integrations, eligibility, decision support, approvals, offers, agreements and settlement.

  3. Adds servicing

    Full Asset Finance

    For institutions running the whole book

    Adds servicing, payments, reconciliation, statements, collections, restructuring, recovery, asset lifecycle, portfolio and audit.

  4. Lead configuration

    Green Mobility Edition

    For e-mobility, battery and clean-energy programmes

    Adds vehicle and battery, charging and swapping, telematics, warranty, insurance, maintenance, fleet, end-of-life and sustainability data.

  5. Adds scale

    Enterprise Edition

    For multi-country groups, fleets, employers and programmes

    Adds multi-country, entity and portfolio configuration, enterprise identity, advanced controls, deployment options and managed support.

Common questions

Plan the right first implementation.

Share your operating model and we will confirm fit, scope and integrations during discovery.

Ask the product team a question
Can suppliers use the platform with several financing partners?

Yes, supplier-led workflows can be configured around approved financing partners, asset eligibility, application routing and settlement responsibilities. Exact routing and data-sharing rules are agreed during implementation.

Does it only support e-bikes?

No. Green mobility is the lead specialist configuration. The same governed foundation can support solar, clean-energy, agricultural, medical, vehicle and other productive assets where the product model is approved.

Can the platform support a digital-lending implementation?

Yes, the controlled origination and servicing foundation can be scoped for an approved digital-lending programme, including onboarding, permitted identity and provider integrations, product configuration, human decisions, disbursement, repayment allocation, collections, audit and reporting. A broader lending or credit-decision programme starts with FinTech Engineering.

Can it integrate with mobile money, banks and accounting systems?

The platform supports integration patterns for payment, banking, accounting and related providers. Named providers and regional availability are confirmed only after technical verification.

Does the platform make automated lending decisions?

It can orchestrate approved rules, scores and evidence, but accountable people and financing institutions retain decision authority. Consequential AI or automation requires explicit controls and review.

Build your asset-finance operating model

Give your board a decision-ready view of the platform.

Tell us about your suppliers, financing model, target markets, assets and integration landscape. We will shape a focused demonstration and implementation path.

How evaluation works

  1. 01Role-based demonstrationSupplier, credit, operations and portfolio journeys with your operating model.
  2. 02Architecture and controls reviewIntegrations, data flows, security and the responsibility model.
  3. 03Scoped implementation planEdition, markets, integrations and a phased release path.
WhatsApp us